If you sold a rental property tomorrow, do you know the exact day your Capital Gains Tax would be due? Not roughly. The actual date. Most landlords assume it goes on the usual Self Assessment return the following January. For a UK home that isn’t your main residence, that assumption is wrong, and it’s an expensive one to find out about late.
The short answer: you must report the sale and pay any Capital Gains Tax within 60 days of completion. Not exchange, not the end of the tax year. Completion. The report goes through HMRC’s online Capital Gains Tax on UK property service, separately from your Self Assessment.
Key points
- For UK residential property with a completion date on or after 27 October 2021, you report and pay within 60 days. Before that the limit was 30 days.
- From 6 April 2026, gains are taxed at 18% within your basic rate band and 24% above it.
- The tax-free allowance (the Annual Exempt Amount) is £3,000 for each person. Joint owners each have their own.
- Miss the deadline and HMRC can charge interest and a penalty, even if your Self Assessment is filed on time later.
When do I have to pay Capital Gains Tax on a rental property?
Within 60 days of the completion date. GOV.UK’s guidance on reporting and paying Capital Gains Tax (opens in a new tab) is plain about it: you must report and pay any tax due on UK residential property within 60 days of completing the sale, and you may have to pay interest and a penalty if you don’t.
The trap is timing. A sale already involves solicitors, an agent and a completion date that can slip. Everyone’s attention is on getting the keys handed over, and the 60 days can open and close while nobody is looking. You still include the sale on your Self Assessment return afterwards. The two aren’t a choice between one or the other: the 60-day report comes first, on its own timetable.
What are the Capital Gains Tax rates for 2026/27?
18% and 24%. GOV.UK’s Capital Gains Tax rates page (opens in a new tab) sets out how it works for gains made from 6 April 2026:
- Take your taxable income for the year (income after your Personal Allowance).
- Take your total taxable gains and deduct the £3,000 allowance.
- Add the two together. The part of the gain that fits within the basic rate band is taxed at 18%. Anything above it is taxed at 24%.
A higher or additional rate taxpayer pays 24% on the whole taxable gain. The basic rate band is £37,700 of taxable income in 2026/27 (£12,571 to £50,270 before the Personal Allowance comes off), so a large gain can easily straddle both rates.
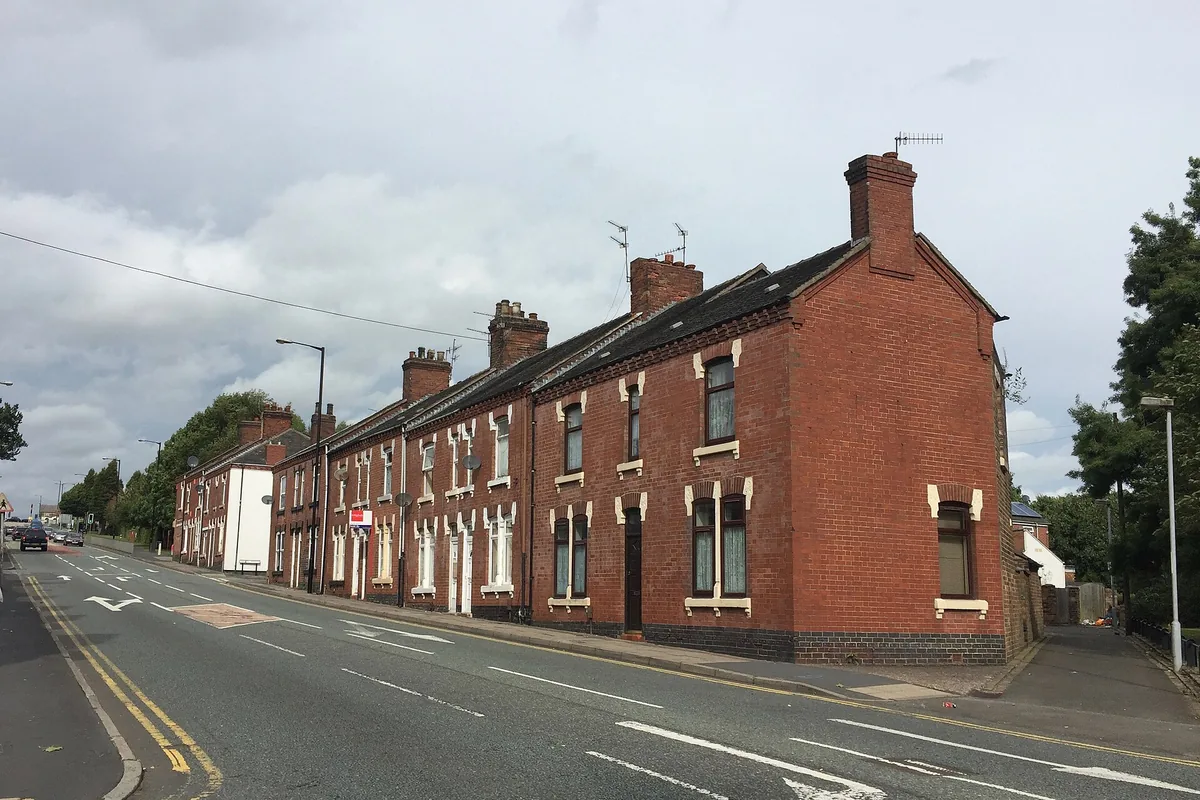
What would that look like on a Stoke-on-Trent terrace?
An illustration, not a tax calculation for your sale. HM Land Registry’s UK House Price Index (opens in a new tab) puts the average terraced house in Stoke-on-Trent at £127,868 in August 2026. Say you sell at that price a terrace you bought for £90,000, with £6,500 of allowable costs (legal fees and Stamp Duty when you bought, agent and legal fees when you sell). The purchase price and costs are made up for the example.
| Step | Amount |
|---|---|
| Sale price | £127,868 |
| Less purchase price and allowable costs | £96,500 |
| Gain | £31,368 |
| Less the £3,000 allowance | £28,368 |
| Tax for a higher rate taxpayer (24%) | £6,808 |
| Tax with £25,000 of taxable income (£12,700 at 18%, £15,668 at 24%) | £6,046 |
Either way, that is around £6,000 to £7,000 to find within 60 days of completion. If the house is owned jointly, each owner works out tax on their own share, with their own £3,000 allowance and their own income.
What costs can I deduct from the gain?
The costs of buying, selling and improving the property. GOV.UK’s guide to tax when you sell property (opens in a new tab) lists estate agents’ and solicitors’ fees and improvement works, such as an extension. Normal maintenance, such as decorating, doesn’t count, and nor does interest on the loan you used to buy the property. Keep the invoices: the deduction is only as good as the paperwork behind it.
Is there any relief if I used to live there?
Yes. If the property was once your main home, Private Residence Relief (opens in a new tab) covers the years you lived there, plus the last 9 months you owned it, even if you weren’t living there by then. The rest of the gain is taxable.
Letting Relief is much narrower than it used to be. It now applies only if you lived in the home at the same time as your tenants, so it rules out most straightforward buy-to-lets. Both reliefs are worth having an accountant check line by line, rather than assuming either way.
Does the 60-day rule apply if the property is in a limited company?
No. A company doesn’t pay Capital Gains Tax. Its gains are charged to Corporation Tax (opens in a new tab) and reported through the company’s own tax return, not the personal 60-day service. It is one more thread in the personal-or-company decision, which we cover in Own It Personally or Through a Company?
What should I do before I sell?
Work out the likely bill before you accept an offer, not after completion when the clock is already running.
- Find your purchase price and costs. The completion statement from when you bought, Stamp Duty paid and any invoices for improvement work.
- Estimate your sale price and selling costs. Agent and solicitor fees count.
- Check your income for the tax year of completion. It decides how much of the gain falls at 18% and how much at 24%.
- Check for reliefs if you ever lived there.
- Set up access to HMRC’s Capital Gains Tax on UK property service before completion, so the report is a formality, not a scramble.
- Put the money aside from the sale proceeds on completion day.
Questions landlords are asking
How long do I have to pay Capital Gains Tax after selling a rental property?
60 days from the completion date, for UK residential property that completed on or after 27 October 2021. You report and pay through HMRC’s Capital Gains Tax on UK property service.
Do I still need to put the sale on my Self Assessment return?
Yes. The 60-day report comes first, and the sale is then included on your Self Assessment return for that tax year. Doing one doesn’t replace the other.
What is the Capital Gains Tax allowance for 2026/27?
£3,000 per person (£1,500 for trusts). Joint owners each have their own allowance to set against their share of the gain.
What happens if I miss the 60-day deadline?
HMRC says you may have to pay interest and a penalty. That applies even if everything is later filed correctly on your Self Assessment return.
Do I pay Capital Gains Tax when selling my own home?
Usually not, because Private Residence Relief covers your main home. You may pay some if you let it out, used part of it for business, or it is very large.
If you’re weighing up when to sell, or how a sale fits with the rest of your portfolio, ask us a question. If you’d like a quicker, more certain route to completion than the open market, see Sell My Home. For the other tax deadline landlords are facing, see our Making Tax Digital guide.
The 60-day rule doesn’t change what you owe. It changes how quickly you need to know.
Rates, allowances and deadlines are from GOV.UK, checked on 10 November 2026. The worked example uses HM Land Registry’s average terraced price for Stoke-on-Trent (August 2026) with a made-up purchase price and costs; it is an illustration, not a calculation for your sale. This post combines two earlier P-Pulse posts on the 60-day rule. The cover photo shows Chorley Street, Leek, by Alan Murray-Rust (Geograph via Wikimedia Commons (opens in a new tab), CC BY-SA 2.0, cropped). This article is general information, not tax, financial or legal advice. Speak to a qualified accountant about your own sale.